 CurveBlock

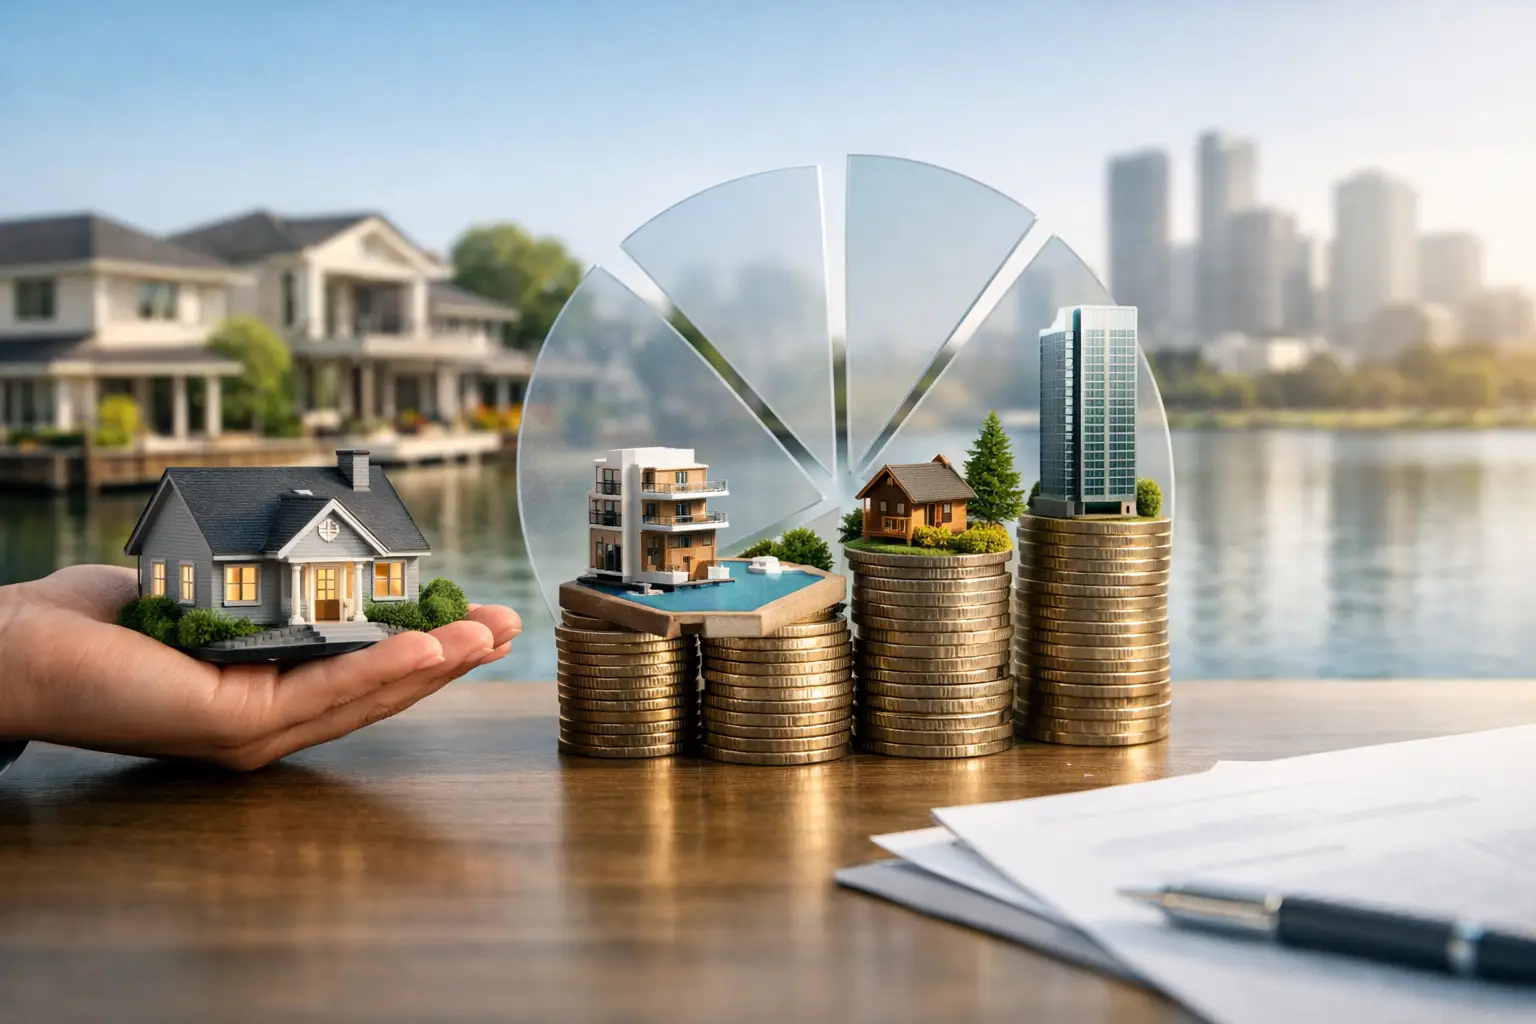
House prices can rise while rental yields fall because capital value growth can outpace rent growth so that the ratio of annual rent to purchase price declines even though landlords receive higher rent in cash terms.
Basic concepts of capital growth and rental yield
When people talk about returns from property they usually mean two related things. Capital growth is the change in the value of a property over time. Rental income is the cash flow a property produces. Rental yield is a simple ratio that compares annual rent to the price paid. Gross yield equals annual rent divided by price and is often expressed as a percentage.
For example a hypothetical property let for £10 000 a year that sells for £200 000 has a gross yield of 5 percent. If the same property later sells for £300 000 while rent rises to £12 000 the gross yield becomes 4 percent because price growth was faster than rent growth. This is a simple illustration of how yields can move opposite to prices.
Yield is a ratio between income and price so changes in either side change the yield.
Why house prices can rise broadly speaking
House prices move for many reasons that are not directly linked to rental income. Demand and supply fundamentals matter. Limited land supply planning constraints and the pace of new build can keep available stock tight. Monetary conditions such as mortgage interest rates and lending availability influence what buyers can afford and therefore what they will pay. Expectations about future economic growth and inflation can lift demand for property as a store of value.
Separately investors and owner occupiers may value properties differently. Buyers who expect price appreciation or who are seeking a place to live will pay more even when rent levels are unchanged. Foreign investment demographic change and changes in household formation can also push prices up without an immediate equivalent rise in market rents.
Price is what buyers will pay today and that can be driven by broader demand unrelated to current rent levels.
Mechanics of yield compression and why yields fall
Yield compression happens when capital values rise faster than rents. Expanding buyer pools lower yields because the denominator of the yield equation increases more quickly than the numerator. This effect is especially marked when investors accept lower income yield in exchange for potential capital gains or for perceived safety relative to other asset classes.
Other forces can reduce the income side. Rent controls local market weakness or change in tenant affordability can cap rent growth. At the same time costs for owners such as insurance maintenance and compliance can rise and reduce net yield even when gross rents rise. The pace of wage growth and household budgets also matter because tenants can only pay so much before demand shifts.
Consider a hypothetical example to make this concrete. Imagine a building that produced £24 000 a year in rent and sold for £480 000 so the gross yield was 5 percent. If interest from buyers and limited supply pushes the sale price to £720 000 while rent increases to £30 000 the gross yield falls to 4.17 percent. Rent rose by 25 percent but price rose by 50 percent so income returns as a share of price fell.
Even rising rents do not prevent yields falling when prices grow faster than rents.
Gross yield net yield and other cost considerations
Gross yield is only a starting point. Net yield subtracts costs associated with owning and operating a property such as management fees void periods maintenance and capital works. Taxation and transaction costs on sale and purchase also affect the investor s net return. High expenditure on energy upgrades or retrofits may depress near term net yield while improving asset value and tenant appeal for the long term.
For portfolio investors pooled exposure can smooth some of these costs and void risk. Different ownership structures and investment vehicles change how income and capital appreciation flow to investors. If a fund is investing to improve energy performance or to meet regulatory requirements the near term yield picture can look weaker while capital value improves over the longer term. For discussion of how retrofit costs are handled in a pooled fund see How retrofits and energy upgrades are funded approved and communicated to digital shareholders.
Net yield depends on many cost items and can diverge from gross yield in important ways.
Expectations liquidity and investor preferences matter
Yields are not a physical law. They reflect what investors require given alternatives. If other assets such as government bonds offer very low yields investors may accept a lower rental yield for property reflecting a lower required return. Conversely if bond yields rise investors demand higher property yields and prices may fall.
Liquidity and transaction speed also feed valuations. Properties that are easier to sell or that are part of larger pooled holdings can attract a premium which reduces yield. The way investors access property markets is changing. Technology can reduce friction in investing small amounts which can widen the investor base and influence pricing. For example see How open banking and bank APIs can speed up investing small amounts in digital shares to learn about some of the plumbing that can change who participates.
Some regulated platforms provide pooled access to a diversified portfolio of properties and projects. CurveBlock is a UK platform approved for Gate 1 of the Bank of England and FCA Digital Securities Sandbox. Sandbox approval is not full FCA authorisation. Platform and regulatory design choices affect liquidity distribution of costs and how income is shared among investors holding digital shares on a long term basis.
Investor expectations about future returns can change prices today and so alter yields even without immediate changes in rent.
Practical implications for different types of investors
Owner occupiers who plan to live in a property care mostly about affordability and suitability rather than yield. Buy to let investors focus on income and tax treatment as well as capital prospects. Long term investors such as pension funds may prioritise total return and stability and accept lower income yields in exchange for steady capital growth.
Diversification is an important tool because property markets are local and outcomes vary by location building type and tenant profile. A split between income producing assets and growth oriented assets reduces the chance that a fall in yields in one segment will derail an investor s broader plan. Always consider the full set of costs and the timeframe over which you expect to hold an investment.
Different investors will interpret the same yield and price signals in different ways according to their objectives.
Frequently asked questions
Why can yields fall even when rents are rising?
Yields fall when property prices increase faster than rents so the ratio of annual rent to price declines even though nominal rent has gone up.
Does a falling yield mean property is a bad investment?
Not necessarily because total return includes both income and capital gain and a falling yield can reflect strong capital growth which may be appropriate for some investors.
How should I compare investments with different yields?
Look at expected total return risk liquidity and time horizon rather than yield alone and take into account costs taxes and management requirements.
Can policy change quickly reverse yield trends?
Yes changes in interest rates tax or rental regulation can alter investor required returns and lead to price moves that change yields.
Where can I learn more about fund level cost recovery for upgrades?
See guidance on how retrofit and energy upgrade costs are managed and reported to digital shareholders in pooled funds.
Questions about yields are best answered by considering both income and capital alongside costs and investor objectives.
General information about the CurveBlock platform. Not financial, legal or tax advice. Capital is at risk. The value of digital shares can fall as well as rise. Past performance is not a guide to future returns.